
As an emerging strategic industry under the global carbon-neutral vision, the new energy vehicle sector has experienced explosive growth, and the EV battery pack has become one of the most critical components determining vehicle performance, cost, and safety. In this study, I focus on a leading Chinese EV battery pack manufacturer (hereafter referred to as “N Company”) and conduct a comprehensive financial performance evaluation using a combination of the entropy weight method and the Data Envelopment Analysis (DEA) approach. I collect longitudinal financial data from 2015 to 2023 for N Company and cross-sectional data from 47 peer enterprises in 2023. After normalizing the raw indicators with the entropy weight technique, I apply the DEA-BCC model to compute comprehensive technical efficiency, pure technical efficiency, and scale efficiency for each decision-making unit (DMU). I further conduct projection analyses to identify input redundancies and output shortfalls in four dimensions: profitability, development capability, operation capability, and solvency. The empirical results reveal that N Company achieved optimal efficiency in 2016 and 2017, but its efficiency declined significantly afterward due to technological innovation lags and resource allocation inefficiencies. The horizontal comparison indicates a clear polarization in the industry, with only a few enterprises reaching full efficiency while most second-tier firms face both technical and scale challenges. Based on these findings, I propose targeted recommendations including strengthening R&D in solid-state and condensed-matter batteries, optimizing financial leverage, enhancing talent cultivation, and promoting inter-firm cooperation. This study contributes to the performance evaluation literature for the EV battery pack industry and offers practical implications for managers, investors, and policy makers.
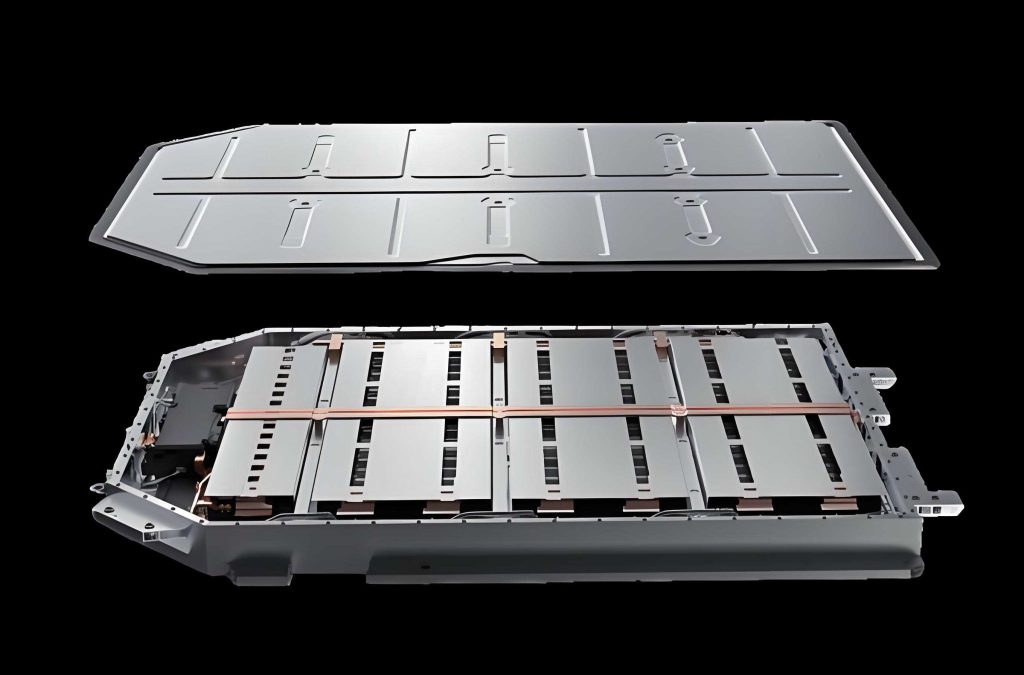
1. Introduction
The global push toward carbon peak and carbon neutrality has accelerated the transition of the transportation and energy sectors. According to the China Association of Automobile Manufacturers, new energy vehicle sales in 2023 reached 9.495 million units, a year-on-year increase of 37.9%, with a market penetration rate of 31.6%. The EV battery pack is the core energy storage unit of electric vehicles, and its industry has been designated as a strategic emerging industry in China. However, the industry is currently facing multiple challenges, including subsidy phase-out, volatile raw material prices, safety concerns, and overcapacity. These challenges are exacerbated by the inherently capital-intensive nature of EV battery pack manufacturing, which requires substantial initial investment and long payback periods. Consequently, many enterprises operate under high financial leverage and suboptimal resource allocation, making financial performance evaluation crucial for sustainable development.
In this context, I aim to answer the following questions: What is the current financial performance of leading EV battery pack enterprises? Are their inputs and outputs well matched? Are there input redundancies or output deficiencies? And what specific improvements can be made? To answer these questions, I employ a two-stage methodology: first, the entropy weight method is used to reduce the dimensionality of twelve financial indicators into four composite indicators (profitability, growth, operation, and solvency); second, a DEA-BCC model is applied to evaluate the relative efficiency of each DMU. The study not only fills a gap in the literature by focusing on the EV battery pack industry but also provides actionable insights for enterprise management and industry policy.
2. Theoretical Framework and Literature Review
2.1 Performance Evaluation and Financial Performance Evaluation
Performance evaluation is a systematic management process that measures whether organizational goals are achieved. Financial performance evaluation specifically focuses on the financial health and operational efficiency of an enterprise, using quantitative indicators such as profitability ratios, turnover ratios, leverage ratios, and growth rates. Traditional methods include DuPont analysis, economic value added (EVA), and the balanced scorecard. However, these methods often rely on subjective weighting or fail to handle multiple inputs and outputs simultaneously.
2.2 Data Envelopment Analysis and Its Applications
DEA, first proposed by Charnes, Cooper, and Rhodes in 1978, is a non-parametric linear programming method for evaluating the relative efficiency of DMUs with multiple inputs and outputs. The CCR model assumes constant returns to scale, while the BCC model allows for variable returns to scale. DEA has been widely applied in banking, logistics, manufacturing, and energy sectors. In the field of EV battery pack enterprises, however, DEA-based financial performance studies remain scarce. Most existing studies focus on technology efficiency or material innovation rather than financial performance. Therefore, this study contributes to the literature by integrating entropy weight with DEA in a case study of N Company, a leading EV battery pack manufacturer.
3. Methodology and Model Construction
3.1 Entropy Weight Method
The entropy weight method objectively determines weights based on the information entropy of each indicator. A lower entropy value indicates a higher dispersion of data and thus a larger weight. The steps are as follows:
Step 1: Normalize the original matrix \(X=(x_{ij})_{m\times n}\) using the range normalization approach. To avoid zero values in DEA, I apply a translation of 0.1 and a scale of 90:
$$y_{ij} = \frac{x_{ij}-\min(x_{ij})}{\max(x_{ij})-\min(x_{ij})} \times 90 + 10, \quad \text{for positive indicators}$$
$$y_{ij} = \frac{\max(x_{ij})-x_{ij}}{\max(x_{ij})-\min(x_{ij})} \times 90 + 10, \quad \text{for negative indicators}$$
Step 2: Compute the proportion \(p_{ij}\) of each observation in indicator \(j\):
$$p_{ij} = \frac{y_{ij}}{\sum_{i=1}^{m} y_{ij}}$$
Step 3: Compute the entropy value \(e_j\) for each indicator:
$$e_j = -\frac{1}{\ln m}\sum_{i=1}^{m} p_{ij} \ln p_{ij}$$
Step 4: Compute the difference coefficient \(d_j = 1-e_j\).
Step 5: Compute the weight of each indicator:
$$w_j = \frac{d_j}{\sum_{j=1}^{n} d_j}$$
Step 6: Multiply the normalized values by the weights and sum within each dimension to obtain the composite scores for profitability, development capability, operation capability, and solvency. These composite scores serve as the input and output variables for the DEA model.
3.2 DEA-BCC Model
The BCC model, developed by Banker, Charnes, and Cooper in 1984, assumes variable returns to scale and can decompose comprehensive technical efficiency (TE) into pure technical efficiency (PTE) and scale efficiency (SE). I select the input-oriented BCC model because N Company’s scale is already far ahead of its peers, so the primary concern is whether the existing inputs are being used effectively to maximize outputs. The linear programming formulation of the input-oriented BCC model is:
$$\begin{aligned}
\min \quad & \theta – \varepsilon \left( \sum_{i=1}^{m} s_i^- + \sum_{r=1}^{s} s_r^+ \right) \\
\text{s.t.} \quad & \sum_{j=1}^{n} \lambda_j x_{ij} + s_i^- = \theta x_{i0}, \quad i=1,\dots,m \\
& \sum_{j=1}^{n} \lambda_j y_{rj} – s_r^+ = y_{r0}, \quad r=1,\dots,s \\
& \sum_{j=1}^{n} \lambda_j = 1 \\
& \lambda_j, s_i^-, s_r^+ \ge 0, \quad j=1,\dots,n
\end{aligned}$$
where \(\theta\) is the pure technical efficiency value, \(s_i^-\) and \(s_r^+\) are slack variables representing input redundancy and output shortfall, respectively. When \(\theta=1\), \(s_i^-=0\), and \(s_r^+=0\), the DMU is fully efficient. If \(\theta<1\), the DMU is inefficient and can be improved by adjusting inputs or outputs.
3.3 Indicator Selection and Data Sources
I initially select twelve financial indicators from four categories. The input indicators include solvency ratios (current ratio, quick ratio, cash ratio, asset-liability ratio) and operation ratios (total asset turnover, current asset turnover, accounts receivable turnover). The output indicators include profitability ratios (return on assets, total asset return, gross profit margin) and growth ratios (operating profit growth, total asset growth). All data are obtained from the annual reports of listed companies and the CSMAR database. The detailed indicator list is presented in Table 1.
| Category | Indicator | Code | Type |
|---|---|---|---|
| Solvency | Current Ratio | C1 | Input |
| Quick Ratio | C2 | Input | |
| Cash Ratio | C3 | Input | |
| Asset-Liability Ratio | C4 | Input (negative) | |
| Operation | Total Asset Turnover | Y1 | Input |
| Current Asset Turnover | Y2 | Input | |
| Accounts Receivable Turnover | Y3 | Input | |
| Profitability | Earnings Per Share | L1 | Output |
| Return on Total Assets | L2 | Output | |
| Gross Profit Margin | L3 | Output | |
| Growth | Operating Profit Growth Rate | F1 | Output |
| Total Asset Growth Rate | F2 | Output |
Using the entropy weight method, I reduce these twelve indicators into four composite scores. The entropy weights for the longitudinal analysis (2015-2023) are shown in Table 2, and for the cross-sectional analysis (2023, 47 enterprises) in Table 3.
| Category | Indicator | Entropy | Difference Coefficient | Weight |
|---|---|---|---|---|
| Solvency (32%) | Current Ratio | 0.87 | 0.13 | 0.07 |
| Quick Ratio | 0.89 | 0.11 | 0.06 | |
| Cash Ratio | 0.78 | 0.22 | 0.13 | |
| Asset-Liability Ratio | 0.91 | 0.09 | 0.05 | |
| Operation (20%) | Total Asset Turnover | 0.89 | 0.11 | 0.06 |
| Current Asset Turnover | 0.89 | 0.11 | 0.07 | |
| Accounts Receivable Turnover | 0.88 | 0.12 | 0.07 | |
| Profitability (30%) | Return on Assets | 0.80 | 0.20 | 0.12 |
| Total Asset Return | 0.81 | 0.19 | 0.11 | |
| Gross Profit Margin | 0.88 | 0.12 | 0.07 | |
| Growth (18%) | Operating Profit Growth | 0.87 | 0.13 | 0.08 |
| Total Asset Growth | 0.83 | 0.17 | 0.10 |
| Category | Indicator | Entropy | Difference Coefficient | Weight |
|---|---|---|---|---|
| Solvency (26%) | Current Ratio | 0.99 | 0.01 | 0.02 |
| Quick Ratio | 0.99 | 0.01 | 0.01 | |
| Cash Ratio | 0.84 | 0.16 | 0.20 | |
| Asset-Liability Ratio | 0.98 | 0.02 | 0.03 | |
| Operation (48%) | Total Asset Turnover | 0.95 | 0.05 | 0.06 |
| Current Asset Turnover | 0.93 | 0.07 | 0.09 | |
| Accounts Receivable Turnover | 0.73 | 0.27 | 0.33 | |
| Profitability (20%) | Return on Assets | 0.93 | 0.07 | 0.08 |
| Total Asset Return | 0.96 | 0.04 | 0.05 | |
| Gross Profit Margin | 0.95 | 0.05 | 0.07 | |
| Growth (6%) | Operating Profit Growth | 0.99 | 0.01 | 0.01 |
| Total Asset Growth | 0.96 | 0.04 | 0.05 |
4. Case Study: N Company Overview and Financial Status
N Company, founded in 2011, has become a global leader in EV battery pack production and energy storage systems. Its core business includes power battery systems, lithium battery materials, and energy storage systems. The enterprise is known for its innovative products, such as the Kirin battery, sodium-ion battery, and CTP technology, which have significantly improved energy density and safety. By the end of 2023, the company had an annual production capacity of 552 GWh, and its market share exceeded 35% globally. The company has strategically invested in upstream minerals and downstream partnerships, creating a vertically integrated supply chain for EV battery packs.
To understand the financial context, I present the key financial indicators of N Company from 2019 to 2023 in Table 4.
| Year | Revenue (Billion CNY) | Net Profit (Billion CNY) | Asset Return (%) | Gross Margin (%) |
|---|---|---|---|---|
| 2019 | 457.88 | 50.13 | 5 | 29.06 |
| 2020 | 503.19 | 61.04 | 4 | 27.76 |
| 2021 | 1303.56 | 178.61 | 6 | 26.28 |
| 2022 | 3285.94 | 334.57 | 6 | 20.25 |
| 2023 | 4009.17 | 467.61 | 7 | 22.91 |
From Table 4, N Company has achieved remarkable revenue and profit growth. However, its gross margin declined from 29.06% in 2019 to 20.25% in 2022, indicating cost pressure from raw material prices and price competition. The asset-liability ratio increased from 58.37% in 2019 to 69.34% in 2023, reflecting heavy reliance on external financing. These financial characteristics make the efficiency evaluation particularly relevant.
5. Empirical Results and Analysis
5.1 Longitudinal Efficiency Analysis of N Company (2015-2023)
After applying the entropy weight method to the longitudinal data, I obtain the composite scores for the four dimensions. These scores are then used as inputs (operation and solvency) and outputs (profitability and growth) in the DEA-BCC model. The composite scores are presented in Table 5.
| Year | Profitability | Growth | Operation | Solvency |
|---|---|---|---|---|
| 2015 | 0.13785 | 0.13361 | 0.23880 | 0.11173 |
| 2016 | 0.05594 | 0.06332 | 0.22373 | 0.17952 |
| 2017 | 0.11032 | 0.04725 | 0.23277 | 0.04893 |
| 2018 | 0.09969 | 0.07227 | 0.07176 | 0.01415 |
| 2019 | 0.15984 | 0.10404 | 0.03728 | 0.02702 |
| 2020 | 0.18329 | 0.04098 | 0.02432 | 0.02921 |
| 2021 | 0.19046 | 0.10924 | 0.07061 | 0.10761 |
| 2022 | 0.17765 | 0.14777 | 0.05144 | 0.07186 |
| 2023 | 0.17908 | 0.16493 | 0.05831 | 0.02120 |
Using the DEAP 2.1 software with the input-oriented BCC model, I compute the technical efficiency, pure technical efficiency, scale efficiency, and returns to scale for each year. The results are shown in Table 6.
| Year | Comprehensive TE | Rank | Pure TE | Rank | Scale Efficiency | Rank | Returns to Scale |
|---|---|---|---|---|---|---|---|
| 2015 | 0.486 | 3 | 1.000 | 1 | 0.486 | 4 | Decreasing |
| 2016 | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| 2017 | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| 2018 | 0.248 | 6 | 0.785 | 5 | 0.316 | 6 | Increasing |
| 2019 | 0.098 | 8 | 0.528 | 6 | 0.185 | 9 | Increasing |
| 2020 | 0.251 | 5 | 1.000 | 1 | 0.251 | 8 | Increasing |
| 2021 | 0.347 | 4 | 0.494 | 7 | 0.703 | 3 | Increasing |
| 2022 | 0.172 | 7 | 0.399 | 8 | 0.430 | 5 | Increasing |
| 2023 | 0.095 | 9 | 0.367 | 9 | 0.259 | 7 | Increasing |
| Mean | 0.411 | 0.730 | 0.514 |
The results in Table 6 reveal significant fluctuations in N Company’s efficiency over time. In 2015, the comprehensive technical efficiency was 0.486, and the pure technical efficiency was already 1, indicating that the technology was efficient but the scale was not optimal. In 2016 and 2017, the company achieved the full-efficient status with all three efficiency values equal to 1. This period coincided with the company’s rapid expansion and the introduction of breakthrough products such as the Kirin battery and sodium-ion battery. These innovations greatly enhanced its competitiveness and resource allocation, leading to optimal input-output combinations. However, since 2018, the comprehensive technical efficiency has declined sharply, with a trough of 0.098 in 2019. The pure technical efficiency also fell to 0.528 in 2019 and further to 0.367 in 2023. This downward trend suggests that the company faced increasing technological competition, rising costs, and possibly internal management inefficiencies. The scale efficiency values indicate that the company is generally operating at increasing returns to scale during inefficient years, implying that it could benefit from further scale expansion, but the substantial deficiency in pure technical efficiency indicates a serious technology and management gap.
To provide more detailed guidance, I conduct a projection analysis for the inefficient years. The DEA projection identifies the input redundancies and output shortfalls that need to be corrected. Tables 7 and 8 present the target improvements for output and input indicators, respectively.
| Year | Profitability Standard | Target | S+ | % | Growth Standard | Target | S+ | % |
|---|---|---|---|---|---|---|---|---|
| 2015 | 0.238802 | 0.239 | 0.000 | 0.08% | 0.111727 | 0.112 | 0.000 | 0.24% |
| 2018 | 0.071763 | 0.227 | 0.155 | 216.32% | 0.014154 | 0.126 | 0.112 | 790.21% |
| 2019 | 0.037277 | 0.228 | 0.191 | 511.64% | 0.027022 | 0.111 | 0.084 | 310.78% |
| 2020 | 0.024320 | 0.024 | 0.000 | -1.32% | 0.029208 | 0.029 | 0.000 | -0.71% |
| 2021 | 0.070612 | 0.202 | 0.131 | 186.07% | 0.107611 | 0.108 | 0.000 | 0.36% |
| 2022 | 0.051440 | 0.226 | 0.175 | 339.35% | 0.071861 | 0.144 | 0.072 | 100.39% |
| 2023 | 0.058310 | 0.225 | 0.167 | 285.87% | 0.021202 | 0.156 | 0.135 | 635.78% |
| Year | Operation Standard | Target | S- | % | Solvency Standard | Target | S- | % |
|---|---|---|---|---|---|---|---|---|
| 2015 | 0.133611 | 0.134 | 0.000 | -0.29% | 0.137851 | 0.138 | 0.000 | -0.11% |
| 2018 | 0.072273 | 0.057 | 0.015 | 21.13% | 0.099689 | 0.078 | 0.022 | 21.76% |
| 2019 | 0.104043 | 0.055 | 0.049 | 47.14% | 0.159839 | 0.084 | 0.076 | 47.45% |
| 2020 | 0.040977 | 0.041 | 0.000 | -0.06% | 0.183288 | 0.183 | 0.000 | 0.16% |
| 2021 | 0.109235 | 0.054 | 0.055 | 50.57% | 0.190462 | 0.094 | 0.096 | 50.65% |
| 2022 | 0.147773 | 0.059 | 0.089 | 60.07% | 0.177654 | 0.071 | 0.107 | 60.03% |
| 2023 | 0.164934 | 0.060 | 0.105 | 63.62% | 0.179081 | 0.066 | 0.113 | 63.15% |
The projection results show that in most inefficient years, the company’s operation and solvency inputs are excessively high relative to its profitability and growth outputs. For instance, in 2023, the operation and solvency standard values would need to be reduced by 63.62% and 63.15%, respectively, while profitability and growth outputs would need to be increased by 285.87% and 635.78%, respectively. This suggests a serious mismatch between resource inputs and value creation. The company may be over-investing in assets and maintaining too much solvency capacity (which lowers return) without generating corresponding profits and growth. In practice, this means the company should optimize its asset structure, accelerate asset turnover, and translate its large-scale investments into more effective profit generation.
5.2 Cross-Sectional Efficiency Analysis (2023, 47 Enterprises)
To benchmark N Company against its peers, I collect the 2023 financial data of 47 listed companies in the EV battery pack and related materials industries. After applying the entropy weight method and the DEA-BCC model, I obtain the efficiency results shown in Table 9.
| Enterprise | Comprehensive TE | Rank | Pure TE | Rank | Scale Efficiency | Rank | RTS |
|---|---|---|---|---|---|---|---|
| Guoxuan Hi-Tech | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| Tianqi Lithium | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| BYD | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| Shuangjie Electric | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| Lead Intelligent | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| Xingyuan Material | 1.000 | 1 | 1.000 | 1 | 1.000 | 1 | Constant |
| Yinghe Technology | 0.854 | 8 | 0.885 | 12 | 0.965 | 11 | Increasing |
| Pengfei Energy | 0.843 | 9 | 0.872 | 13 | 0.967 | 10 | Increasing |
| Zhongcai Technology | 0.825 | 10 | 0.842 | 15 | 0.980 | 9 | Increasing |
| Nandu Power | 0.739 | 11 | 1.000 | 1 | 0.739 | 28 | Increasing |
| Yicheng New Energy | 0.738 | 12 | 0.828 | 17 | 0.891 | 18 | Increasing |
| Longbai Group | 0.681 | 13 | 0.920 | 11 | 0.740 | 27 | Increasing |
| Desay Battery | 0.679 | 14 | 0.690 | 28 | 0.984 | 8 | Increasing |
| EVE Energy | 0.665 | 15 | 0.775 | 21 | 0.859 | 20 | Increasing |
| Xinzhoubang | 0.652 | 16 | 0.660 | 30 | 0.987 | 7 | Increasing |
| Meijin Energy | 0.647 | 17 | 0.833 | 16 | 0.776 | 24 | Increasing |
| Hua You Cobalt | 0.642 | 18 | 0.826 | 18 | 0.778 | 23 | Increasing |
| Greenmei | 0.632 | 19 | 0.771 | 22 | 0.819 | 21 | Increasing |
| Tongling Nonferrous | 0.610 | 20 | 0.654 | 32 | 0.932 | 15 | Increasing |
| Wolong Drive | 0.591 | 21 | 0.778 | 20 | 0.760 | 25 | Increasing |
| Duofuduo | 0.570 | 22 | 0.614 | 38 | 0.928 | 16 | Increasing |
| Ganfeng Lithium | 0.565 | 23 | 0.624 | 37 | 0.907 | 17 | Increasing |
| Shanshan | 0.556 | 24 | 0.738 | 25 | 0.753 | 26 | Increasing |
| Daoshi Technology | 0.540 | 25 | 0.569 | 40 | 0.950 | 13 | Increasing |
| Tianyuan Co. | 0.525 | 26 | 0.651 | 33 | 0.807 | 22 | Increasing |
| Zhongkuang Resources | 0.524 | 27 | 1.000 | 1 | 0.524 | 44 | Decreasing |
| Tianci Materials | 0.507 | 28 | 0.693 | 27 | 0.732 | 31 | Increasing |
| Yuntianhua | 0.506 | 29 | 0.722 | 26 | 0.701 | 35 | Increasing |
| Xiamen Tungsten | 0.475 | 30 | 0.789 | 19 | 0.602 | 38 | Increasing |
| Xiangtan Electrochemical | 0.469 | 31 | 0.657 | 31 | 0.714 | 33 | Increasing |
| Nuode | 0.468 | 32 | 0.684 | 29 | 0.684 | 37 | Increasing |
| Sheng Hua New Materials | 0.465 | 33 | 0.632 | 35 | 0.735 | 30 | Increasing |
| Zhongke Electric | 0.451 | 34 | 0.855 | 14 | 0.528 | 43 | Increasing |
| Shengyang Co. | 0.450 | 35 | 0.626 | 36 | 0.719 | 32 | Increasing |
| Weilan Lithium | 0.444 | 36 | 0.758 | 24 | 0.585 | 41 | Increasing |
| Kefeng Co. | 0.380 | 37 | 1.000 | 1 | 0.380 | 45 | Increasing |
| Cangzhou Mingzhu | 0.367 | 38 | 0.531 | 41 | 0.691 | 36 | Increasing |
| Xiongtao Co. | 0.346 | 39 | 0.585 | 39 | 0.590 | 40 | Increasing |
| Dangsheng Tech | 0.341 | 40 | 0.391 | 44 | 0.873 | 19 | Increasing |
| Hongxing Development | 0.262 | 41 | 0.354 | 45 | 0.739 | 28 | Increasing |
| Annada | 0.260 | 42 | 0.440 | 42 | 0.591 | 39 | Increasing |
| Jiangte Motor | 0.243 | 43 | 0.769 | 23 | 0.316 | 46 | Increasing |
| Yahua Group | 0.232 | 44 | 0.412 | 43 | 0.564 | 42 | Increasing |
| Yongxing Materials | 0.221 | 45 | 0.231 | 47 | 0.960 | 12 | Increasing |
| Fangda Carbon | 0.205 | 46 | 0.290 | 46 | 0.706 | 34 | Increasing |
| Aoke Co. | 0.092 | 47 | 0.647 | 34 | 0.143 | 47 | Increasing |
| N Company | 0.095 | 48 | 0.367 | 47 | 0.259 | 45 | Increasing |
| Mean | 0.578 | 0.736 | 0.777 |
From Table 9, only six enterprises (Guoxuan Hi-Tech, Tianqi Lithium, BYD, Shuangjie Electric, Lead Intelligent, and Xingyuan Material) achieve full efficiency. These enterprises exhibit both technical and scale efficiency, indicating that they have reached the optimal combination of technology and scale. N Company, despite being the largest EV battery pack manufacturer by market share, has a surprisingly low comprehensive technical efficiency of 0.095, ranking last among the 47 enterprises. Its pure technical efficiency is 0.367 and scale efficiency is 0.259, both far below the industry averages of 0.736 and 0.777, respectively. This result suggests that N Company’s vast scale has not translated into proportional financial output, reflecting severe input redundancy and output deficiency. The projection analysis for N Company (as part of the 42 inefficient enterprises) is presented in Tables 10 and 11, where the target improvements for inputs and outputs are shown.
| Company | Operation Standard | Target | S- | % | Solvency Standard | Target | S- | % |
|---|---|---|---|---|---|---|---|---|
| Desay Battery | 0.085 | 0.037 | 0.048 | 56.39% | 0.058 | 0.040 | 0.018 | 30.44% |
| Tongling Nonferrous | 0.427 | 0.043 | 0.384 | 89.93% | 0.060 | 0.039 | 0.021 | 34.55% |
| Meijin Energy | 0.117 | 0.059 | 0.058 | 49.66% | 0.044 | 0.037 | 0.007 | 16.73% |
| Zhongcai Technology | 0.037 | 0.032 | 0.005 | 14.66% | 0.048 | 0.040 | 0.008 | 16.62% |
| Cangzhou Mingzhu | 0.030 | 0.016 | 0.014 | 47.15% | 0.075 | 0.040 | 0.035 | 46.60% |
| Xiangtan Electrochemical | 0.050 | 0.032 | 0.018 | 35.73% | 0.059 | 0.039 | 0.020 | 33.74% |
| Annada | 0.126 | 0.055 | 0.071 | 56.28% | 0.084 | 0.037 | 0.047 | 55.78% |
| Jiangte Motor | 0.043 | 0.033 | 0.010 | 22.99% | 0.047 | 0.036 | 0.011 | 24.02% |
| Weilan Lithium | 0.034 | 0.026 | 0.008 | 23.96% | 0.050 | 0.038 | 0.012 | 23.79% |
| Greenmei | 0.047 | 0.037 | 0.010 | 21.90% | 0.050 | 0.038 | 0.012 | 23.86% |
| Tianyuan Co. | 0.438 | 0.054 | 0.384 | 87.67% | 0.057 | 0.037 | 0.020 | 35.47% |
| Duofuduo | 0.045 | 0.027 | 0.018 | 39.38% | 0.066 | 0.041 | 0.025 | 37.97% |
| Ganfeng Lithium | 0.047 | 0.029 | 0.018 | 37.79% | 0.063 | 0.039 | 0.024 | 38.20% |
| Yahua Group | 0.092 | 0.038 | 0.054 | 58.81% | 0.089 | 0.037 | 0.052 | 58.58% |
| Shengyang Co. | 0.059 | 0.037 | 0.022 | 36.79% | 0.061 | 0.038 | 0.023 | 37.54% |
| BYD | 0.099 | 0.099 | 0.000 | 0.50% | 0.046 | 0.046 | 0.000 | -1.00% |
| Longbai Group | 0.062 | 0.022 | 0.040 | 64.56% | 0.043 | 0.039 | 0.004 | 8.91% |
| Tianci Materials | 0.054 | 0.021 | 0.033 | 60.89% | 0.057 | 0.039 | 0.018 | 31.51% |
| Xiongtao Co. | 0.046 | 0.027 | 0.019 | 41.36% | 0.065 | 0.038 | 0.027 | 41.15% |
| Zhongkuang Resources | 0.077 | 0.077 | 0.000 | -0.23% | 0.122 | 0.122 | 0.000 | 0.39% |
| Yongxing Materials | 0.365 | 0.084 | 0.281 | 76.98% | 0.227 | 0.052 | 0.175 | 77.12% |
| EVE Energy | 0.045 | 0.035 | 0.010 | 22.09% | 0.051 | 0.039 | 0.012 | 22.84% |
| Zhongke Electric | 0.027 | 0.023 | 0.004 | 13.66% | 0.045 | 0.038 | 0.007 | 15.49% |
| Xinzhoubang | 0.027 | 0.018 | 0.009 | 33.00% | 0.063 | 0.042 | 0.021 | 33.56% |
| Nandu Power | 0.060 | 0.060 | 0.000 | 0.65% | 0.036 | 0.036 | 0.000 | 1.26% |
| Dangsheng Tech | 0.061 | 0.024 | 0.037 | 60.60% | 0.105 | 0.041 | 0.064 | 60.87% |
| Yicheng New Energy | 0.048 | 0.039 | 0.009 | 18.08% | 0.047 | 0.039 | 0.008 | 16.60% |
| Aoke Co. | 0.098 | 0.046 | 0.052 | 53.01% | 0.054 | 0.035 | 0.019 | 34.93% |
| Zhiyun Co. | 0.021 | 0.021 | 0.000 | 2.23% | 0.043 | 0.043 | 0.000 | 0.38% |
| Kefeng Co. | 0.043 | 0.043 | 0.000 | -0.19% | 0.034 | 0.034 | 0.000 | 1.25% |
| Daoshi Technology | 0.037 | 0.021 | 0.016 | 43.55% | 0.077 | 0.044 | 0.033 | 42.63% |
| Pengfei Energy | 0.031 | 0.027 | 0.004 | 13.15% | 0.048 | 0.042 | 0.006 | 12.85% |
| Yinghe Technology | 0.021 | 0.018 | 0.003 | 15.38% | 0.045 | 0.040 | 0.005 | 10.92% |
| Yuntianhua | 0.444 | 0.016 | 0.428 | 96.39% | 0.055 | 0.040 | 0.015 | 27.83% |
| Nuode | 0.015 | 0.010 | 0.005 | 33.65% | 0.067 | 0.046 | 0.021 | 31.52% |
| Hongxing Development | 0.077 | 0.027 | 0.050 | 64.78% | 0.109 | 0.039 | 0.070 | 64.18% |
| Fangda Carbon | 0.036 | 0.011 | 0.025 | 69.69% | 0.157 | 0.046 | 0.111 | 70.79% |
| Xiamen Tungsten | 0.089 | 0.029 | 0.060 | 67.44% | 0.049 | 0.039 | 0.010 | 20.91% |
| Wolong Drive | 0.043 | 0.033 | 0.010 | 23.33% | 0.049 | 0.038 | 0.011 | 23.15% |
| Shanshan | 0.033 | 0.024 | 0.009 | 27.22% | 0.052 | 0.039 | 0.013 | 25.62% |
| Sheng Hua New Materials | 0.110 | 0.060 | 0.050 | 45.32% | 0.058 | 0.036 | 0.022 | 37.55% |
| Hua You Cobalt | 0.064 | 0.045 | 0.019 | 30.05% | 0.047 | 0.039 | 0.008 | 17.36% |
| N Company | 0.058 | 0.021 | 0.037 | 63.79% | 0.021 | 0.008 | 0.013 | 61.90% |
| Company | Profitability Standard | Target | S+ | % | Growth Standard | Target | S+ | % |
|---|---|---|---|---|---|---|---|---|
| Desay Battery | 0.033 | 0.035 | 0.002 | 4.49% | 0.048 | 0.048 | 0.000 | -0.02% |
| Tongling Nonferrous | 0.031 | 0.032 | 0.001 | 4.10% | 0.045 | 0.045 | 0.000 | 0.79% |
| Meijin Energy | 0.028 | 0.028 | 0.000 | 1.79% | 0.035 | 0.035 | 0.000 | -0.57% |
| Zhongcai Technology | 0.049 | 0.049 | 0.000 | 0.27% | 0.039 | 0.039 | 0.000 | -0.97% |
| Cangzhou Mingzhu | 0.033 | 0.053 | 0.020 | 60.96% | 0.023 | 0.028 | 0.005 | 19.70% |
| Xiangtan Electrochemical | 0.044 | 0.044 | 0.000 | 1.04% | 0.020 | 0.030 | 0.010 | 47.09% |
| Annada | 0.028 | 0.028 | 0.000 | 1.38% | 0.026 | 0.032 | 0.006 | 22.13% |
| Jiangte Motor | 0.014 | 0.023 | 0.009 | 58.97% | 0.012 | 0.020 | 0.008 | 68.18% |
| Weilan Lithium | 0.029 | 0.036 | 0.007 | 22.77% | 0.020 | 0.023 | 0.003 | 16.03% |
| Greenmei | 0.031 | 0.031 | 0.000 | 1.14% | 0.038 | 0.038 | 0.000 | 0.26% |
| Tianyuan Co. | 0.020 | 0.027 | 0.007 | 33.80% | 0.037 | 0.037 | 0.000 | 0.04% |
| Duofuduo | 0.035 | 0.041 | 0.006 | 18.67% | 0.042 | 0.042 | 0.000 | -0.80% |
| Ganfeng Lithium | 0.044 | 0.044 | 0.000 | -0.02% | 0.035 | 0.035 | 0.000 | 0.34% |
| Yahua Group | 0.027 | 0.027 | 0.000 | -1.76% | 0.022 | 0.025 | 0.003 | 15.07% |
| Shengyang Co. | 0.038 | 0.038 | 0.000 | -1.19% | 0.027 | 0.029 | 0.002 | 8.73% |
| BYD | 0.089 | 0.089 | 0.000 | 0.29% | 0.053 | 0.053 | 0.000 | -0.22% |
| Longbai Group | 0.050 | 0.050 | 0.000 | 0.64% | 0.029 | 0.029 | 0.000 | 1.28% |
| Tianci Materials | 0.050 | 0.050 | 0.000 | -0.68% | 0.017 | 0.029 | 0.012 | 69.53% |
| Xiongtao Co. | 0.036 | 0.036 | 0.000 | 1.07% | 0.014 | 0.024 | 0.010 | 71.69% |
| Zhongkuang Resources | 0.088 | 0.088 | 0.000 | 0.49% | 0.053 | 0.053 | 0.000 | -0.59% |
| Yongxing Materials | 0.099 | 0.099 | 0.000 | 0.51% | 0.023 | 0.045 | 0.022 | 99.40% |
| EVE Energy | 0.045 | 0.045 | 0.000 | -0.64% | 0.033 | 0.033 | 0.000 | 0.49% |
| Zhongke Electric | 0.030 | 0.041 | 0.011 | 36.67% | 0.014 | 0.025 | 0.011 | 76.44% |
| Xinzhoubang | 0.051 | 0.051 | 0.000 | -0.74% | 0.034 | 0.034 | 0.000 | 0.28% |
| Nandu Power | 0.025 | 0.025 | 0.000 | 0.15% | 0.033 | 0.033 | 0.000 | -0.16% |
| Dangsheng Tech | 0.059 | 0.059 | 0.000 | 0.31% | 0.007 | 0.030 | 0.023 | 353.31% |
| Yicheng New Energy | 0.026 | 0.030 | 0.004 | 14.29% | 0.042 | 0.042 | 0.000 | -1.05% |
| Aoke Co. | 0.009 | 0.009 | 0.000 | -5.05% | 0.005 | 0.019 | 0.014 | 293.62% |
| Zhiyun Co. | 0.062 | 0.062 | 0.000 | 0.66% | 0.007 | 0.029 | 0.022 | 342.41% |
| Kefeng Co. | 0.006 | 0.006 | 0.000 | -1.09% | 0.016 | 0.016 | 0.000 | -0.51% |
| Daoshi Technology | 0.030 | 0.038 | 0.008 | 26.62% | 0.044 | 0.044 | 0.000 | -0.07% |
| Pengfei Energy | 0.031 | 0.037 | 0.006 | 20.06% | 0.046 | 0.046 | 0.000 | 0.42% |
| Yinghe Technology | 0.053 | 0.053 | 0.000 | 0.48% | 0.028 | 0.028 | 0.000 | -1.64% |
| Yuntianhua | 0.055 | 0.055 | 0.000 | 0.37% | 0.021 | 0.028 | 0.007 | 31.94% |
| Nuode | 0.027 | 0.055 | 0.028 | 104.71% | 0.029 | 0.035 | 0.006 | 19.15% |
| Hongxing Development | 0.030 | 0.038 | 0.008 | 28.16% | 0.030 | 0.030 | 0.000 | -1.50% |
| Fangda Carbon | 0.034 | 0.055 | 0.021 | 63.15% | 0.028 | 0.034 | 0.006 | 20.31% |
| Xiamen Tungsten | 0.046 | 0.046 | 0.000 | 0.72% | 0.021 | 0.030 | 0.009 | 41.08% |
| Wolong Drive | 0.042 | 0.042 | 0.000 | 0.35% | 0.026 | 0.030 | 0.004 | 13.49% |
| Shanshan | 0.034 | 0.041 | 0.007 | 21.55% | 0.028 | 0.028 | 0.000 | -1.62% |
| Sheng Hua New Materials | 0.020 | 0.025 | 0.005 | 27.05% | 0.033 | 0.033 | 0.000 | 0.16% |
| Hua You Cobalt | 0.045 | 0.045 | 0.000 | 0.49% | 0.033 | 0.033 | 0.000 | -0.55% |
| N Company | 0.179 | 0.225 | 0.046 | 25.70% | 0.165 | 0.225 | 0.060 | 36.36% |
The cross-sectional projection results for N Company indicate that its profitability output should be increased by 25.70% and its growth output by 36.36% while its operation and solvency inputs should be reduced by 63.79% and 61.90%, respectively. This implies that N Company, despite its leadership in EV battery pack production, has not been able to convert its massive asset base and solvency capacity into commensurate financial returns. The large input redundancies suggest overinvestment in assets and excessive liquidity that could be better deployed. The company needs to streamline its asset structure, reduce idle resources, and focus on high-margin products and more efficient production processes.
6. Problems Revealed by the Evaluation
6.1 Technological Innovation Lag and Efficiency Fluctuation
N Company achieved full efficiency in 2016 and 2017, but its efficiency dropped significantly afterward. This decline is closely related to the lag in technological innovation. While the company introduced the Kirin battery and sodium-ion battery earlier, subsequent breakthroughs in solid-state and condensed-matter battery technologies have been relatively slow. Competitors have made rapid progress in battery energy density, fast-charging capabilities, and safety features, eroding N Company’s technological moat. The DEA results show that pure technical efficiency fell from 1 in 2017 to 0.367 in 2023, highlighting the urgent need for renewed innovation.
6.2 Overcapacity and Inefficient Resource Allocation
The scale efficiency values below 0.8 for most years, combined with increasing returns to scale, indicate that N Company is still expanding its production capacity. However, the market demand for EV battery packs is subject to fluctuations due to policy changes, technological shifts, and competition. The rapid expansion has led to overcapacity, idle assets, and high inventory costs, reducing asset turnover and return on investment. The input projection shows that a substantial portion of the operation and solvency inputs is redundant, further confirming the problem of resource misallocation.
6.3 High Financial Leverage Risk
N Company’s asset-liability ratio increased from 44.76% in 2016 to 69.34% in 2023. While financial leverage helps to expand production and fund R&D, it also increases interest expenses and repayment pressure. In an economic downturn, a high debt ratio could lead to liquidity crises. The solvency input redundancy identified by the DEA suggests that the company may be holding excessive liquid assets that could be used more productively. Balancing the benefits and risks of leverage is essential for long-term stability.
6.4 Insufficient Talent Development and Incentive Mechanisms
The EV battery pack industry is technology-intensive and requires highly skilled professionals. N Company, like most enterprises, faces challenges in attracting and retaining top talent. The lack of targeted incentive mechanisms, such as dedicated career ladders for technical staff and equity incentive plans, may lead to high turnover rates. The decrease in pure technical efficiency could partly be attributed to the inability to maintain a highly motivated and innovative workforce.
7. Policy Recommendations
7.1 Strengthen R&D and Expand into Storage and Commercial Vehicle Markets
First, N Company should increase R&D investment in next-generation battery technologies, including solid-state batteries and condensed-matter batteries, while continuing to improve the energy density and safety of the existing EV battery pack products. Establishing joint laboratories with universities and research institutions can accelerate technology breakthroughs and shorten the R&D cycle. Second, the company should actively exploit the energy storage market, which is growing rapidly due to the increasing share of renewable energy. Large-scale production of storage batteries can create new profit growth points and reduce dependence on the volatile automotive market. Third, the company should diversify its customer base by entering the commercial vehicle segment, covering buses, logistics vehicles, and light trucks, as well as exploring emerging applications in aviation equipment, intelligent machinery, and medical devices. This market expansion can enhance profitability and strengthen cash flow.
7.2 Optimize Financial Leverage and Capital Structure
N Company should set a reasonable target debt ratio based on its cash flow stability and capital needs. It should reduce over-reliance on short-term borrowing and diversify financing channels, such as issuing long-term bonds, equity financing, and strategic partnership investments. The company should also implement dynamic cash flow management to ensure sufficient liquidity for debt repayment and to avoid liquidity crises. By optimizing the capital structure, the company can lower financial risk and improve its financial performance.
7.3 Emphasize Talent Cultivation and Differentiated Competition
Establishing a comprehensive professional training system is critical. The company should provide continuous education and skill-upgrading programs for employees, build a clear promotion path for technical professionals, and design effective incentive schemes, including stock options, project bonuses, and recognition awards. Differentiated competition is also essential. Leading enterprises should focus on high-end technology and brand value, while second-tier enterprises should compete by cost optimization and service quality. All enterprises should strengthen cooperation through technical sharing and joint development to improve the overall efficiency of the EV battery pack industry.
7.4 Promote Collaboration and Industry Upgrading
Enterprises should form technology innovation alliances to share R&D resources and reduce duplication of effort. Cross-enterprise cooperation on common key technologies, such as solid-state electrolytes and advanced battery management systems, can accelerate progress and lower costs. Second-tier companies should seek diversified financing through IPOs, private placements, mergers, and acquisitions to consolidate production capacity and improve industry concentration. Strengthening collaborations along the supply chain, from raw material suppliers to vehicle makers, will promote a healthy industrial ecosystem and enhance the international competitiveness of China’s EV battery pack industry.
7.5 Government Policy Guidance and Support
Governments should continue to provide subsidies and tax incentives for R&D and market expansion, but with well-designed performance benchmarks to avoid inefficiency. Policies that encourage the adoption of high-performance, high-safety EV battery packs can help accelerate the phase-out of obsolete technologies. International cooperation should be facilitated through free trade agreements and export support to help domestic enterprises expand globally. Meanwhile, setting stricter safety and quality standards will push enterprises to improve their products and operations, thereby increasing the overall efficiency of the industry.
8. Conclusion and Future Research
In this study, I developed a financial performance evaluation framework for EV battery pack enterprises by integrating the entropy weight method and DEA. The case study of N Company reveals that its efficiency was optimal during 2016-2017 but deteriorated significantly in the following years. The longitudinal analysis shows that the company has increasingly suffered from input redundancy and output insufficiency, especially in terms of profitability and growth. The cross-sectional analysis of 47 enterprises indicates a polarized industry landscape: only six enterprises achieved full technical and scale efficiency, while the majority, including N Company, still face considerable efficiency gaps. The projection analysis provides specific target improvement values, which can guide management actions.
Based on these findings, I recommend that N Company prioritize technological innovation in advanced battery technologies, optimize its capital structure, enhance talent development and incentive systems, and pursue market diversification in storage and commercial vehicle applications. Additionally, greater industry collaboration and supportive government policies are necessary for the long-term health of the EV battery pack sector.
This research has several limitations. First, I relied solely on financial data and omitted non-financial indicators such as customer satisfaction, employee engagement, and environmental performance, which may affect the comprehensiveness of the evaluation. Second, the sample is limited to 47 listed enterprises, and the cross-sectional comparison is only for one year. Future research could expand the sample to include unlisted firms and use panel data to capture dynamic efficiency changes. Third, the application of super-efficiency DEA and the Malmquist index could provide deeper insights into the evolution of total factor productivity in the EV battery pack industry.
In summary, the proposed entropy-DEA framework offers a robust and practical tool for evaluating the financial performance of EV battery pack enterprises. The empirical evidence highlights the importance of aligning resource inputs with market demands and technological advancements. By implementing the suggested improvements, N Company and its peers can enhance their efficiency and contribute to the sustainable development of the global new energy industry.